Government Consultation Offers Further Clarity on Business and Agricultural Property Relief
The 2024 Autumn Budget left many people unsure how much inheritance tax their beneficiaries will now have to pay on their business and agricultural assets. A recent two-month consultation launched by the government has provided further clarity, offering an opportunity for testators and settlors to plan ahead.
Autumn Budget Relief Cuts
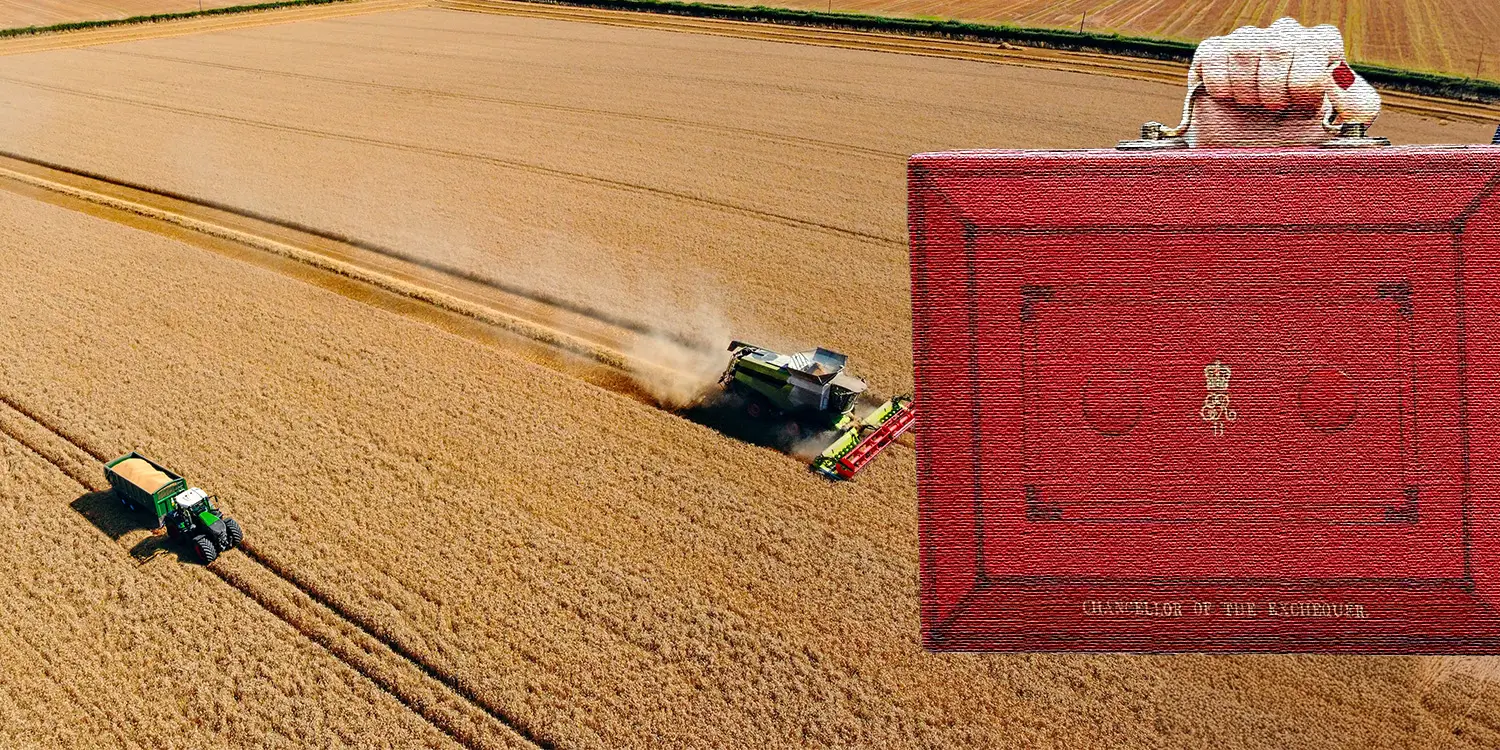
Currently, Agricultural Property Relief (APR) applies at a 100% rate on the Agricultural Value of qualifying assets and Business Property Relief (BPR) applies at 100% on qualifying assets. No inheritance tax (IHT) is payable on a testator’s assets with an agricultural character, including farmland, farmhouses and agricultural buildings. Inherited assets used in a trading business, such as buildings, shares in companies, certain plant and machinery also attract 100% relief.
As most people now know, in the Autumn Budget the Government cut the relief to 50% above the first £1 million. In effect from 6 April 2026, this introduces a 50% tax on those qualifying assets over £1 million, leaving farmers and business owners wondering how their beneficiaries will cope with what may be significant sums to pay.
In response to the significant pushback (particularly from farmers), many repudiated the objections and suggested farmers simply put their property into trust to evade the IHT liability. The recent consultation has offered some clarity but suggests the implementation of this ‘solution’ will be far more complicated than it first appears.
Transfers into Trust
After implementation of the new rules, many transfers into trust will be liable to IHT upfront only if the value exceeds £1.65 million where all allowances are available. The first £1 million will be covered by the APR/BPR allowance, and the remaining £650,000 will attract a 50% relief, leaving £325,000 which will be covered by the settlor’s nil rate band.
It was confirmed that transfers made to trust between the Budget announcement and 5 April 2026, the ‘transitional period’, will be subject to the existing rules. However, if the settlor dies after the transitional period but within the ordinary seven-year period following the gift, the new rules will apply.
The consultation proposed an anti-fragmentation rule for property put into trust on or after 30 October 2024. If the settlor transfers qualifying property to multiple trusts, then the Government suggests that there will only be one £1 million 100% APR or BPR allowance. That allowance will be allocated in chronological order, with the earlier settlements to benefit first. This fixed allocation will apply for the lifetime of the trust.
On a positive note, the £1 million allowance will not be a single lifetime allowance. Instead, it will be similar to the nil-rate band and refresh every seven years. This means, subject to the intricacies of trust planning, parents could be able to put business or agricultural assets in trust for their child and transfer quite significant value over time without upfront IHT liability.
Also like the operation of the nil-rate band, potentially exempt transfers (PETs) will not deplete the £1 million allowance if the donor survives the requisite seven years after the gift.
Further Clarifications
A disappointing confirmation is that the £1 million allowance will not be transferable between spouses. This will be disheartening to farmers particularly, who have underlined the potential the relief cuts have to drive the fragmentation of family-owned farms.
As a possible relief for some, the clarification sets out that from 6 April 2026, any property qualifying for APR or BPR will be eligible for interest free instalment payments. This means that the IHT due can be paid in equal annual amounts over a ten-year period. This eases the pressure on some, but those inheriting farms and businesses with limited profit margins will undoubtedly still struggle.
The consultation has offered a medley of confirmations, suggestions, and proposals. Whilst many concerns have been upheld, and some contradicted, we will not have complete clarity on the specifics until the consultation closes on 23 April 2025. As it stands, however, it is clearer than ever that effective tax planning and professional advice is crucial in ensuring your beneficiaries enjoy the assets you leave to them.
With professional guidance, the convolution of IHT efficiency can be navigated and assets protected. For expert advice on effective tax planning, contact one of our specialist solicitors here at Nantes.
Expert Advice on Navigating IHT Changes:
At Nantes Solicitors, we specialise in helping individuals and businesses understand the impact of APR and BPR cuts on their estates. With offices in
Bridport,
Dorchester, Weymouth, and
Portland, our expert team provides tailored tax planning advice to protect your assets and minimise liabilities. Get in touch to ensure your estate is structured efficiently for the future.